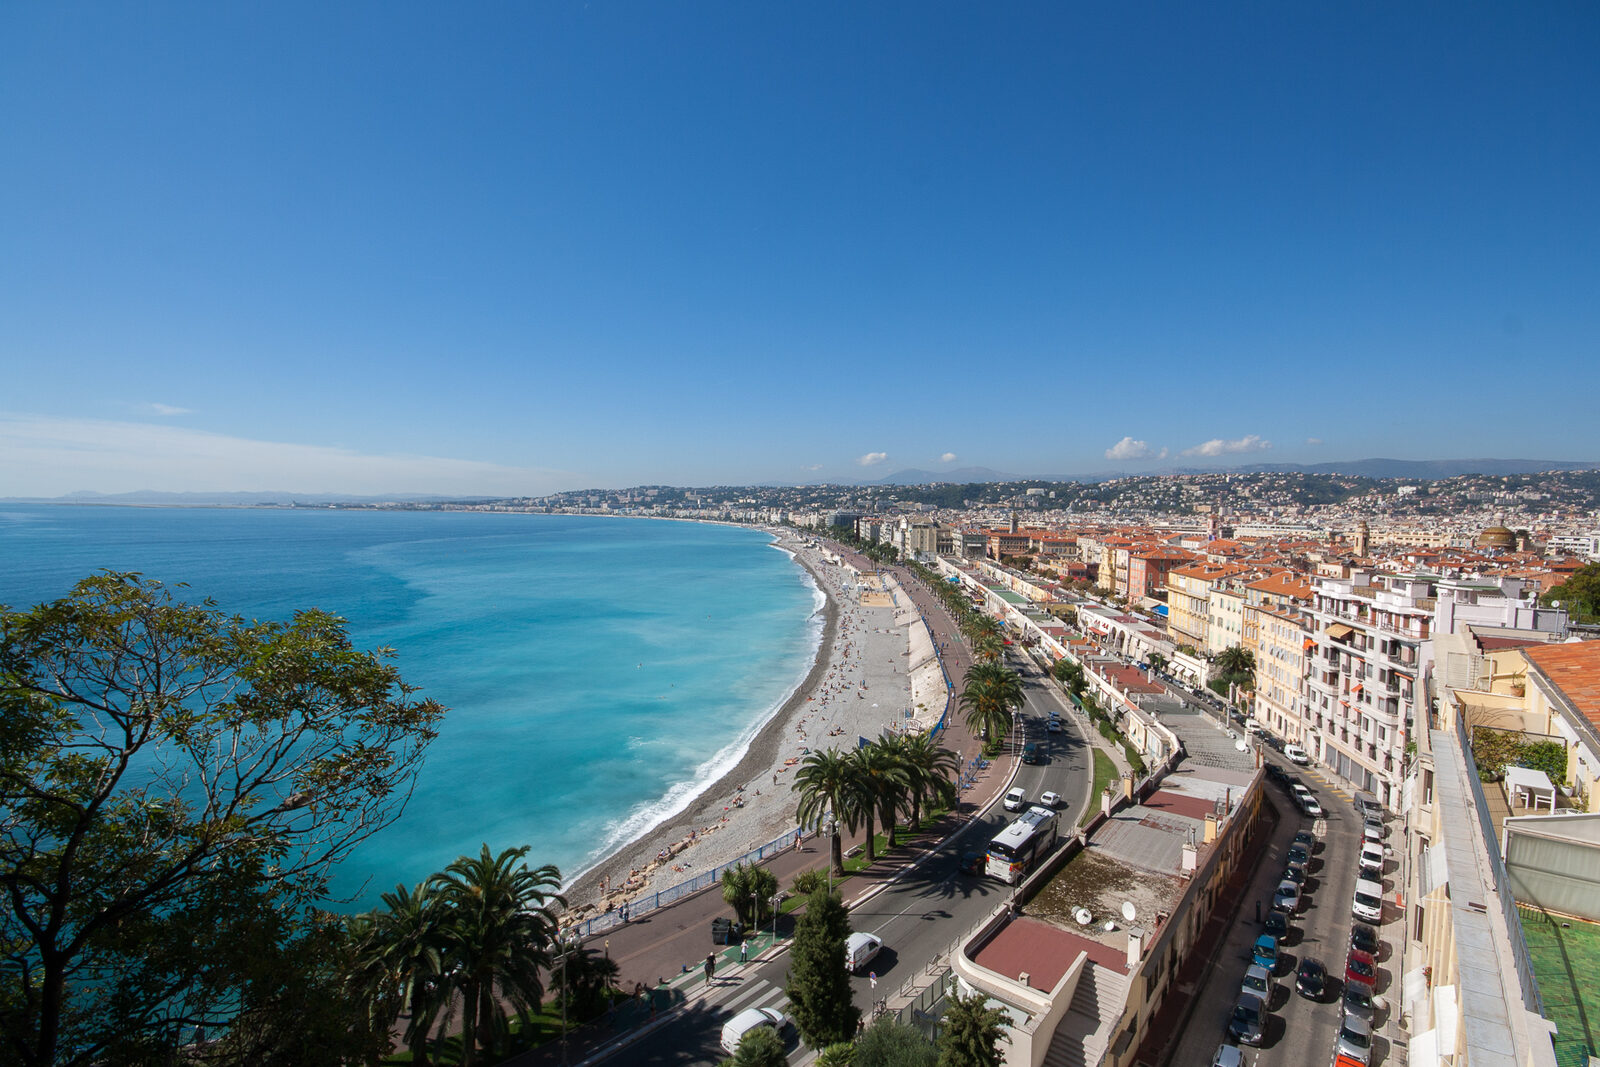
Looking for a mortgage broker in Nice to finance an apartment in Carré d'Or, a house in Cimiez or a rental investment in Vieux-Nice? I am Audrey Hurelle, an independent mortgage broker based on the Côte d'Azur. I help buyers in Nice — first-time buyers, families, investors and non-residents — secure finance that genuinely suits their plans. My role is to build a strong application, approach banks that match your circumstances and negotiate the full package: your mortgage, insurance, fees and repayment flexibility, right through to completion with the notaire (the French conveyancing notary).
The property market in Nice
Average property prices in Nice are around €5,200 per square metre, with substantial differences between neighbourhoods: from €3,800 in l'Ariane to as much as €12,000 on the Promenade des Anglais. Your lending strategy must reflect that diversity: a bank willing to finance a one-bedroom apartment in Riquier may take a different view of a three-bedroom apartment with sea views in Cimiez.
Nice remains one of France's most active property markets. Bank processing takes longer than in other regional markets — allow 8–10 weeks — and lenders apply stricter income criteria.
Non-residents account for a significant share of buyers in Nice. Only a handful of banks accept international applications: using a local broker saves you weeks approaching unsuitable lenders.
The rates available in Nice depend on your circumstances and the neighbourhood you are buying in. For strong applications, I regularly secure rates 0.20–0.40 percentage points below branches' advertised rate schedules.
Tram lines 1, 2 and 3 have reshaped the price map: connected areas such as western Nice and Saint-Roch attract first-time buyers and investors. Banks favour these locations because properties are easier to resell and let.
Short-term furnished letting in Nice is now regulated, with authorisations and change-of-use requirements. Before financing a holiday rental investment, I check with you that it would also be viable as a conventional rental, something banks examine closely.
My speciality in Nice: applications banks find complicated
Nice attracts buyers whose circumstances standard bank criteria too often overlook: self-employed professionals, people with international income, returning expats and buyers combining a main home purchase with existing loans. These are precisely the applications I handle most often in Nice.
In practice, that means assessing your income over three financial years if you are self-employed, documenting earnings received outside France or balancing repayments across several loans to meet debt-to-income requirements. This work happens before your application reaches the first bank.
Another feature of Nice is its older housing stock: apartment buildings dating from the 1930s to the 1970s, properties needing renovation in Vieux-Nice or Riquier, and homes with a DPE (energy performance rating) of F or G. Banks pay close attention to this. I help you cost the work and include it in your mortgage from the outset, rather than discovering the expense after signing.
Buying in Nice also often means moving quickly: the best properties sell within days. Having an agreement in principle ready before you start viewing lets you make a credible offer, ahead of buyers who have not yet spoken to their bank.
The neighbourhoods of Nice where I work
Carré d'Or & Promenade
Nice's most sought-after area. High prices (€8,000–€12,000/m²) come with strict bank requirements for deposits and income. I know which lenders finance these premium properties.
Vieux-Nice & Port
Historic character, with properties often needing renovation. Banks require detailed building quotes and sometimes release funds in stages: the finance needs planning ahead.
Cimiez & Mont Boron
Upmarket residential neighbourhoods with spacious homes and sea views, calling for wealth-focused financing. I structure applications combining a main home purchase with balanced repayments on existing loans.
Libération, Saint-Roch, Riquier
Neighbourhoods growing in value, ideal for first-time buyers and investors. More accessible prices (€4,500–€6,500/m²) and strong rental demand.
Nice Ouest (Saint-Augustin, Arenas)
New developments and VEFA (off-plan purchases). I negotiate the specific terms, including reduced notaire fees, PTZ (the French zero-interest first-time-buyer loan) and balanced repayments across your loans.
Fabron, Magnan & Caucade
Residential hills in western Nice, offering apartments with terraces and sea views at lower prices than the Promenade. Popular with families and well suited to buying your first main home.
Gairaut, Saint-Pancrace & Rimiez
Peaceful houses and villas in the hills. Banks assess the land value and the property's condition: I prepare an application that brings these strengths to the fore.
Musiciens & Gambetta
Elegant period buildings close to gare Thiers and the tram, with strong demand for student and furnished rentals. An excellent area for your first rental investment.
How I support your purchase in Nice
1. Free discovery call (30 minutes)
We discuss your plans, finances and timing. I give you an honest assessment of whether your purchase can be financed and on what terms.
2. Full review and strategy
I analyse your income, deposit and existing loans. Together, we build the strongest possible application, and I select the 3–5 banks best suited to your circumstances and your purchase in Nice.
3. Negotiation
I present your application to my direct branch contacts and negotiate the interest rate, mortgage protection insurance, arrangement fees and early repayment terms.
4. Support through to completion
I support you from the mortgage offer through to signing with the notaire, including arranging insurance with an alternative provider and the release of funds.
Why choose me as your broker in Nice
- ✓ Detailed knowledge of Nice's banks and their internal lending criteria
- ✓ Direct branch contacts: no platform and no extra intermediary
- ✓ Personal support: I reply to every email and call myself
- ✓ Specialist support for the non-resident and international buyers so common in Nice
- ✓ Fees payable only when your loan is secured and accepted
Free discovery call · 30 min
Book a free call with Audrey about your French mortgage
In English, by video. Reply within 24 business hours. No obligation.
FAQ — Mortgage broker in Nice
- The discovery call and financial review are free. My brokerage fee is 2% of the amount borrowed, with a €4,500 minimum, payable only when you have signed and accepted the loan.
- Allow an average of 8–10 weeks between the compromis de vente (preliminary sale agreement) and completion with the notaire, compared with 6–8 weeks in other regional markets.
- Banks generally expect a minimum deposit of 10%. In premium neighbourhoods, a deposit of 15–20% makes your application considerably stronger.
- Yes, this is one of my specialities. I work in French and English with banks that finance international buyers.
- Absolutely. I support many rental investments in Nice, including unfurnished, furnished, LMNP (France's non-professional furnished letting status) and short-term rentals.
- For strong applications, I regularly secure rates 0.20–0.40 percentage points below branches' advertised rate schedules.
- Yes. Banks generally require two to three years of accounts. I present your income clearly — its average, trend and your company's cash position — and target lenders familiar with independent professionals and business owners.
- Yes, provided you supply detailed quotes before the mortgage offer. Renovation funds are released against invoices. This is often the best solution for properties in Vieux-Nice or homes rated DPE F or G.
- It does not prevent a mortgage for a main home, but the bank takes it into account when valuing the property. For a rental investment, letting restrictions make a costed renovation plan essential; I include this in your application.
- It is strongly recommended. An affordability assessment and a financing feasibility certificate help you make a credible offer quickly, which matters greatly in a competitive market like Nice.