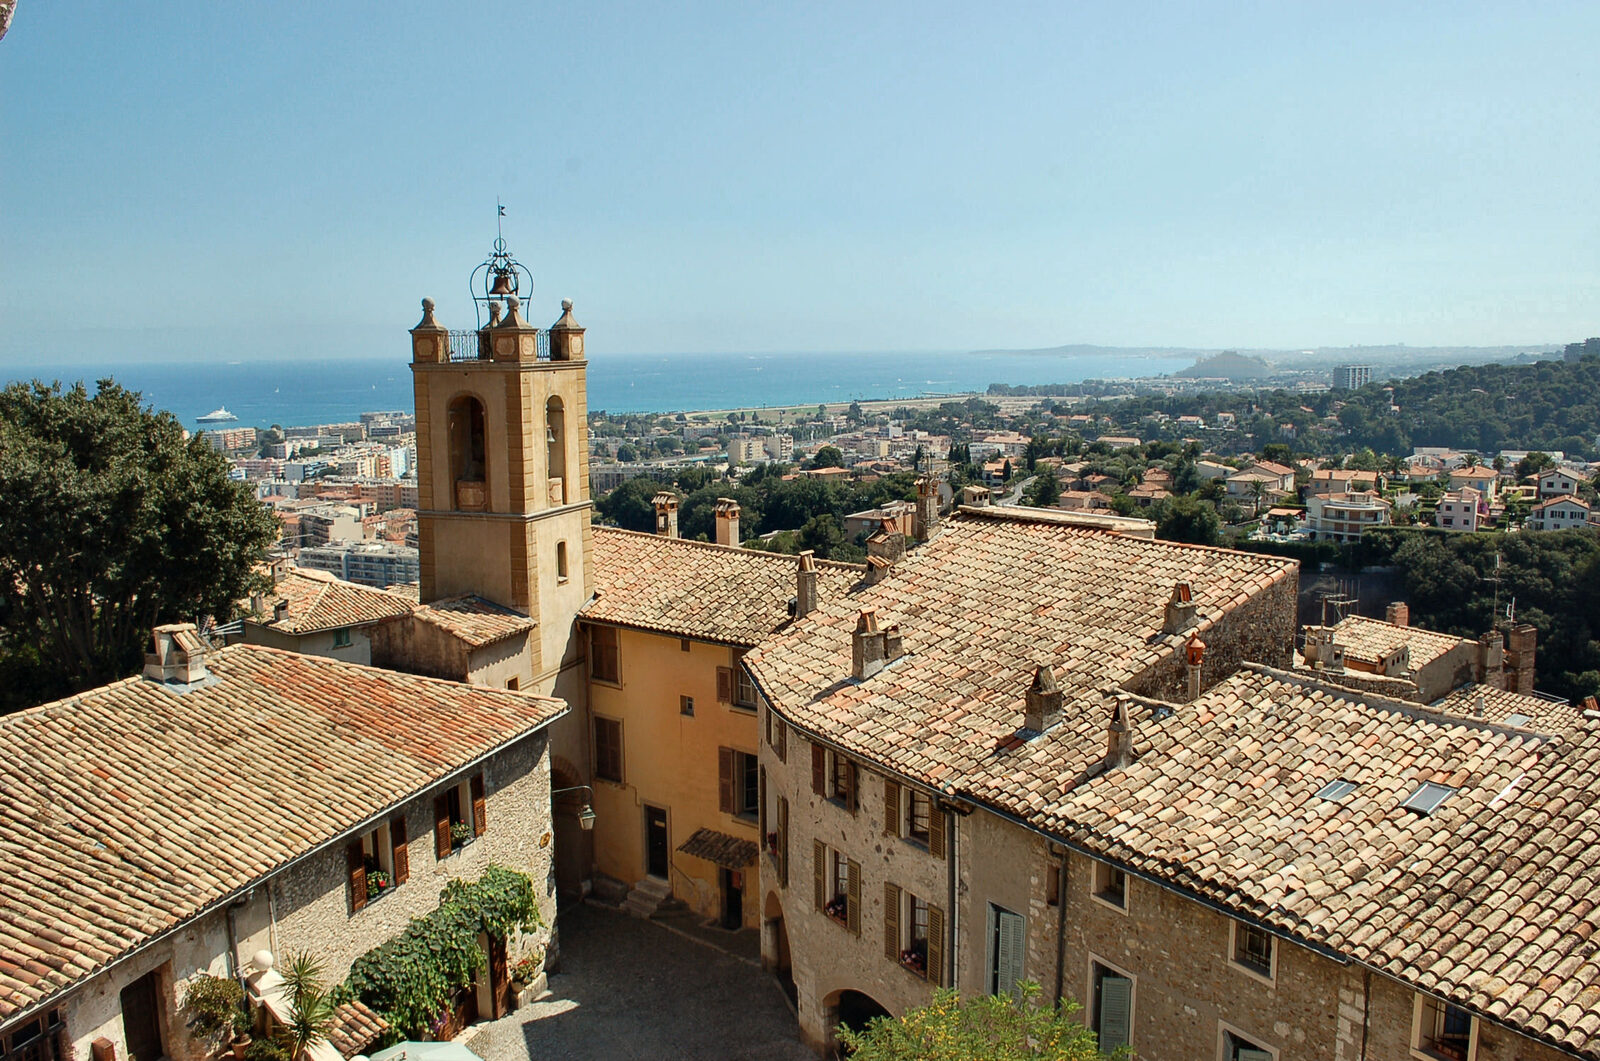
Looking for a mortgage broker in Cagnes-sur-Mer to finance an apartment in l'Hippodrome, a house in Haut-de-Cagnes or a second home in Cros-de-Cagnes? I am Audrey Hurelle, an independent mortgage broker based on the Côte d'Azur. Every month, I help first-time buyers, families and investors in Cagnes secure the best mortgage for their plans, with genuinely personal support and no fees before the loan is secured.
The property market in Cagnes-sur-Mer
Average property prices in Cagnes-sur-Mer are around €4,700 per square metre, with a marked gap between the Cros-de-Cagnes seafront (up to €6,500/m²) and the town centre (€4,000–€4,500/m²). This relative affordability makes Cagnes a favourite with first-time buyers in the Nice area, offering some of the best value on the Côte d'Azur.
Cagnes-sur-Mer is the natural alternative to Nice for first-time buyers: prices per square metre are 25–35% lower, with tram T3, the A8 and TER regional trains reaching Nice-Ville in 15 minutes.
Properties remain easy to buy and sell, reassuring lenders and helping secure more favourable terms than in Nice itself, including rates, insurance and loan security.
The town attracts families leaving Nice for more space on the same budget, alongside rental investors drawn by student and holiday demand.
My speciality in Cagnes-sur-Mer: your first home purchase
Cagnes is where I support the most first-time purchases in the Nice area. My typical clients here have a budget for a one- or two-bedroom apartment, often with a deposit covering only notaire (the French conveyancing notary) fees. Many are couples buying for the first time.
Three things make the difference for these purchases: securing a PTZ (the French zero-interest first-time-buyer loan) where available, showing the bank that you will retain a reassuring savings buffer, and obtaining a financing feasibility certificate before viewing properties so you do not lose out to a buyer whose funding is already in place.
The neighbourhoods of Cagnes-sur-Mer where I work
Hippodrome & Bord de mer
Modern residences, sea-view apartments and strong demand. Prices are firm (€5,000–€6,500/m²), and service charges can be high: I select banks that accept these properties without compromising your required disposable income.
Cros-de-Cagnes
An authentic fishing village with a competitive property market. Older homes often need renovation: I coordinate the mortgage and renovation finance, eligibility for MaPrimeRénov' (the state renovation grant) and staged fund releases.
Haut-de-Cagnes
Medieval character, village houses and scarce properties. Banks consider the age of the building and its DPE (energy performance rating): I approach lenders that finance this type of heritage property.
Centre-ville & Val Fleuri
Accessible prices for first-time buyers (€4,000–€5,000/m²), close to the SNCF railway station, with strong rental demand. Ideal for a first purchase or rental investment.
Les Vespins & Les Collettes
Quiet residential areas popular with families and retirees. Detached houses and straightforward mortgages: regional banks are particularly competitive for these buyers.
How I support your purchase in Cagnes-sur-Mer
1. Free discovery call (30 minutes)
We discuss your plans in Cagnes-sur-Mer, your circumstances and timing. I give you an honest view of what is possible and the rate to aim for.
2. Financial review and lending strategy
I analyse your income, deposit and existing loans, then select the 3–5 banks best suited to your purchase in Cagnes.
3. Negotiation
I present your application in branch and negotiate the interest rate, mortgage protection insurance, arrangement fees and early repayment terms.
4. Support through to completion
I support you from the mortgage offer through to signing with the notaire, including arranging insurance with an alternative provider and the release of funds.
Why choose me as your broker in Cagnes-sur-Mer
- ✓ Detailed knowledge of the Cagnes market and its distinctive areas: Hippodrome, Cros and Haut-de-Cagnes
- ✓ Direct contacts at bank branches throughout the Alpes-Maritimes (06)
- ✓ Personal support: I reply to every email and call myself
- ✓ Specialist in first-time purchases and rental investment between Antibes and Nice
- ✓ Fees payable only when your loan is secured and accepted
Free discovery call · 30 min
Book a free call with Audrey about your French mortgage
In English, by video. Reply within 24 business hours. No obligation.
FAQ — Mortgage broker in Cagnes-sur-Mer
- The discovery call and financial review are free. My fee is 2% of the amount borrowed, with a €4,500 minimum, payable only when you sign and accept the mortgage negotiated for you.
- Banks expect at least 10% to cover notaire fees and loan security costs. A 15% deposit gives you access to much better terms, particularly for apartments around l'Hippodrome.
- Yes. Cagnes-sur-Mer is in zone B1, making a new-build main home eligible for a PTZ, subject to income limits. I include it in your financing plan where appropriate.
- Allow 8–10 weeks between the compromis de vente (preliminary sale agreement) and completion with the notaire, as elsewhere in the Alpes-Maritimes (06).
- Yes. It is one of the most attractive towns in the Alpes-Maritimes (06) for rental investment, with student and holiday demand and nearby tram connections. I regularly arrange finance for LMNP (France's non-professional furnished letting status) and unfurnished rental investments in Cagnes.
- Either works. Most of my clients in Cagnes prefer video calls to save time, but I can also meet you if you prefer.
- Yes. I regularly arrange mortgages with renovation finance in Cros. We include building quotes in the financing plan and align fund releases with progress on site.
- Yes, and I always recommend it. Within 48 hours of our call, you receive a document stating your maximum budget. Estate agents in Cagnes increasingly ask for this before accepting an offer.
- It depends on your deposit, existing loans and mortgage term. Rather than focusing on salary alone, I calculate your actual borrowing capacity during the discovery call, including insurance and the disposable income required by banks in the Alpes-Maritimes (06).
- It is rare but not impossible, particularly for a rental investment or a younger buyer with strong income progression. You will need savings left over and an impeccable application. I tell you during our first call whether it is realistic.